
Storm damage
Storm damage and insurance claims
Yes, we work with insurance companies. Most of our roofs are paid for by the homeowner, but after a hailstorm most of them aren’t, and we’ve been through a lot of claims.
When a claim is involved, we’re on your side of the table.
If something just happened
Call the office at 517-485-9886. If it’s after hours, leave a message and we’ll call you back the next business morning. If a tree is on the roof, it has to come off before anyone can do anything, so we’ll be out once it’s off and get the house dried in.
We’ll tell you exactly what we can do and when.
How a claim usually goes
- We come out and look. Andy gets on the roof, photographs the damage, and measures.
- You call your insurance company and open a claim. It’s your claim and your policy, so that call is yours to make.
- The adjuster comes out. Andy can meet them there, so the person who measured your roof and the person paying for it are looking at the same thing.
- The numbers get matched up. Our estimate and the adjuster’s are built the same way, line by line. If one of us missed something, we photograph it and send it in until the paperwork matches your roof.
- You see it all before you sign. You’ll understand every line of it.
- We put the roof on. Same crews, same day on site, same cleanup as any other job.
Why our numbers and your adjuster’s line up
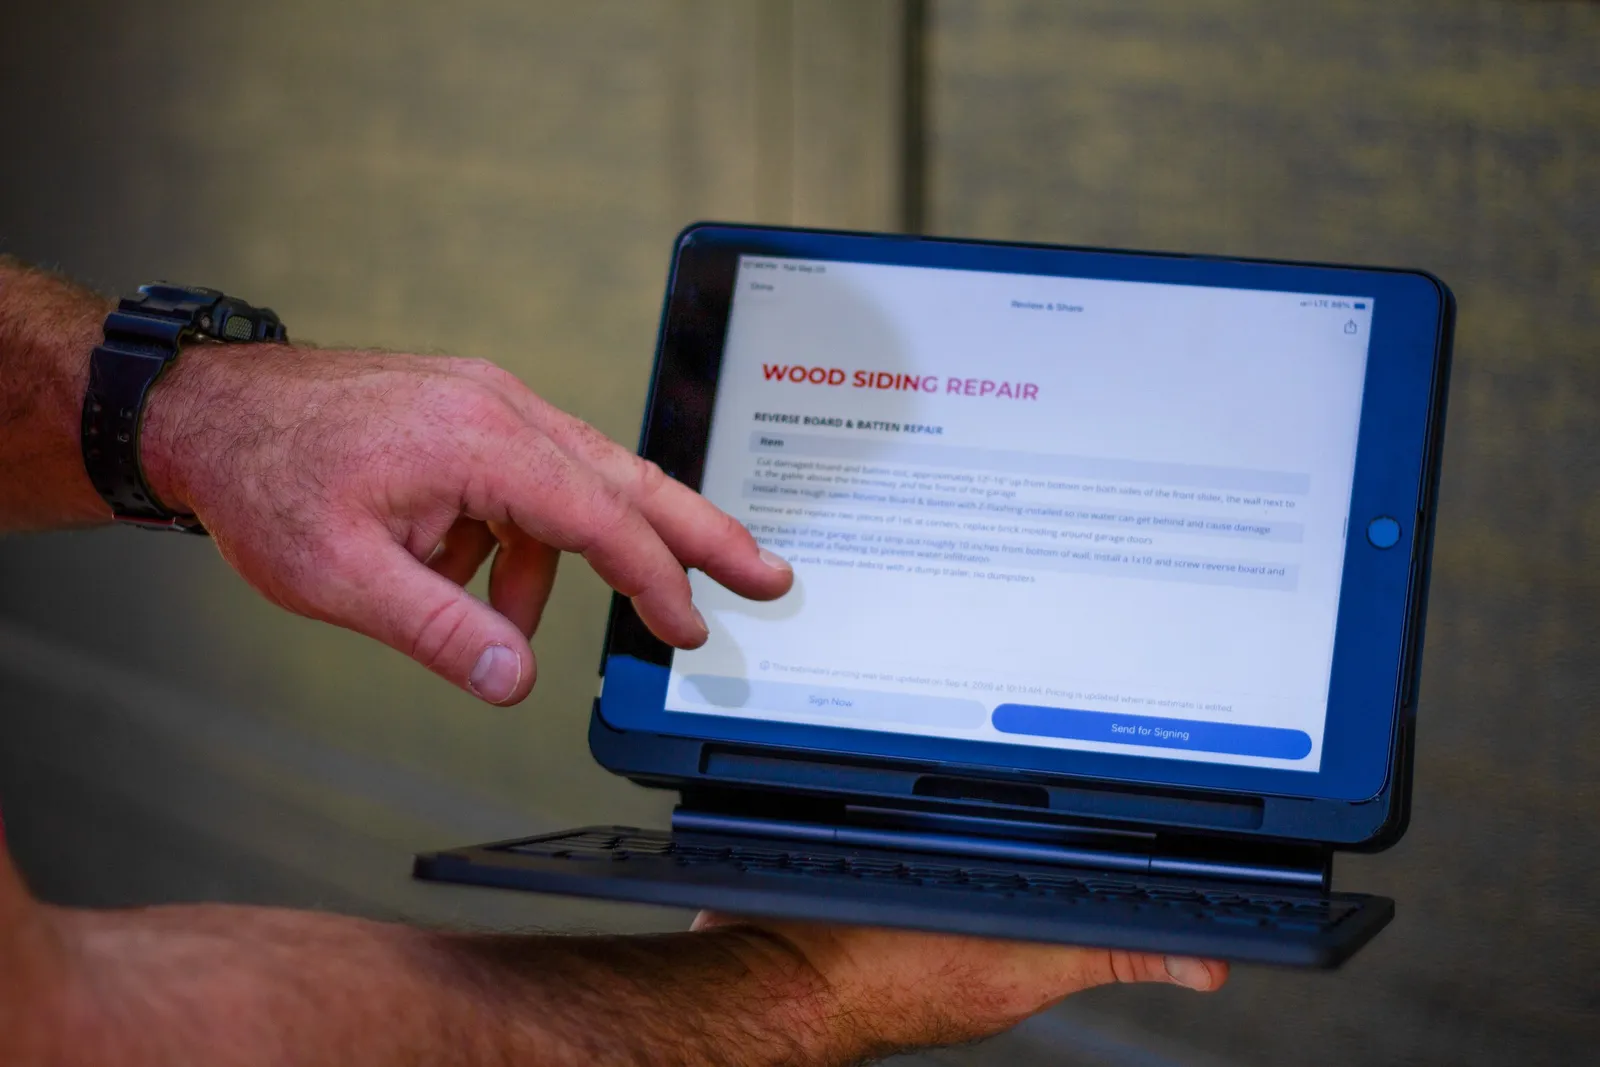
We write insurance estimates the same way insurance companies do: itemized, down to the lineal feet of drip edge. When Andy and the adjuster meet, they’re working from the same quantities and the same line items, so there’s less to argue about.
If something real was left off, we go back up, take pictures, and send them.
The paperwork he held onto
A farmer had a hail claim and was holding his insurance paperwork close, sure he was about to get taken. Andy sat with him at the kitchen table and explained it line by line. Afterward he asked Andy to come back a second time just to go over the paperwork again, and told him he liked him because he’d actually explained things.
Common questions
- Do you work with my insurance company?
Yes. We work with whichever company you have.
- Do I have to use my insurance company’s contractor?
You choose who puts your roof on. Your insurance company may suggest contractors, and the choice is still yours.
- Will my premium go up if I file a claim?
That’s a question for your agent; it depends on your policy and your company. We can tell you whether the damage is real and what it would take to fix.
- What’s a supplement?
If more damage turns up once the work starts, rotten wood under the shingles for instance, it goes back to the insurance company with photos as an addition to the original claim. That’s a supplement. You’ll hear about it from us before anything is added.
- What if they say no?
Sometimes the damage isn’t there, and we’ll tell you if it isn’t. If it is and something got missed, we send photos until the paperwork matches what’s on the roof. The decision is the insurance company’s, and we’ll help you understand it.
Storm come through? Call the office, and we’ll come out and look.